
Home Other Blogs Could Stablecoins Transform Cr...
CIO Bulletin
,
06 October, 2026
Author:
Ravathi Sunil
Imagine a coffee importer in Seattle attempting to send $50,000 to a mid-sized bean supplier in Colombia.
It sounds like a simple, routine corporate transaction. Yet under the legacy financial architecture, that wire must embark on a multi-day journey. It passes through intermediary correspondent banks, triggers opaque foreign exchange markups, incurs steep flat fees, and vanishes into a black box for three business days. If the wire hits a weekend or a local bank holiday, cash flow grinds to a halt.
These inefficiencies, which the international business had to put up with for many decades, are now being challenged by modern corporate finance as it becomes real-time oriented. The key question that comes to the fore is whether stablecoin payments can change international business.
And the short answer is yes.
The Anatomy of the Legacy Friction Point
By analyzing the difficulties associated with traditional cross-border payments, one can comprehend the reasons behind the popularity of stablecoins.
The global payment network depends mostly on the correspondent banking system. As a result, in case when two countries do not have any direct banking relationship, the money passes through many intermediate banks. Each such step implies the addition of a processing fee, an FX spread, and a delay in the transaction process. Globally, this problem causes losses of hundreds of billions annually due to transaction fees and lost liquidity.
As for a company that works with a number of overseas suppliers or contractors, the cross-border friction leads to the following issues:
Irregular Processing Time: Transactions may be processed within 24 hours to five business days.
Hidden Charges: In the process of the transaction, intermediary banks hide various fees that cause the recipient to lose part of the sum.
Working Capital Blockage: Companies need to prefund the accounts in foreign currencies to pay their local suppliers.
How Stablecoins Rewrite the B2B Playbook
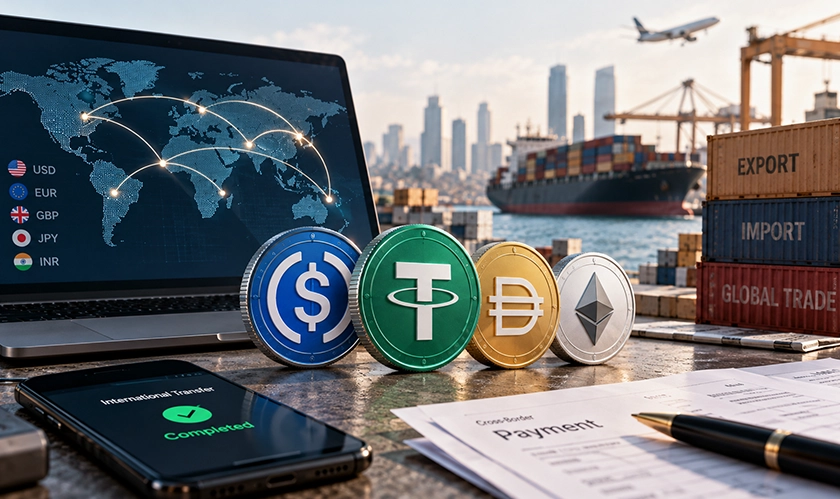
Stablecoins, which are digital assets collateralized on a 1:1 ratio against fiat currencies such as the US dollar or Euro, make it possible to separate value exchange from the timetables of traditional banking systems. Stablecoins are based on public and private blockchain platforms, which enable value transfer directly between the sender and receiver 24/7.
This is how stablecoins solve the key challenges of enterprise cross-border settlements:
Instead of waiting days for batch processing, a stablecoin payment settles on-chain in seconds or minutes, even on a Sunday night. A business in Singapore can settle an invoice with a partner in Brazil before Monday morning trading opens.
By cutting out the chain of intermediary correspondent banks, stablecoin transfers can reduce cross-border transaction costs significantly. On high-throughput blockchain networks, on-chain network fees cost fractions of a cent, allowing companies to save on high-frequency, mid-ticket international payments.
Because transactions are recorded on immutable ledgers, both the buyer and the seller can track the exact status of a payment in real time. There is no mystery about where the funds are stalled or which intermediary deducted a fee.
Stablecoins enable smart contracts, self-executing agreements where funds are released automatically once verified conditions (such as a confirmed bill of lading) are met. This automates escrow, streamlines vendor management, and improves cash predictability.
From Experimental Tech to Enterprise Standard
Back in the day, large enterprises would be wary of the new technology, citing a lack of regulation and integration issues. However, in recent times, there has been a shift from speculation and experimentation to functional utility.
The emergence of regulatory bodies such as the GENIUS Act in the U.S. and MiCA in the EU has made it possible for corporate treasurers to know the legal boundaries within which they can issue reserve-backed payment tokens. Payment processors of today take care of the blockchain technology, KYC/KYB checks, and fiat conversions in the background. For the end-user, sending a stablecoin invoice is akin to making an ACH/SEPA transaction, but with the convenience of instant global settlement in the background.
Examples of major corporate use cases being deployed right now are:
Global Supplier & Vendor Settlements: Making payments directly to international manufacturers without having to pay expensive wire fees.
Distributed Workforce Payroll: Paying distributed staff instantly in many different countries.
Intercompany Treasury Sweeps: Liquidity transfer between multinational subsidiaries instantly overnight without needing to worry about bank cut-offs.
The Path Ahead
Despite the clear benefits offered by stablecoins, issues such as localized off-ramps for fiat money and integration with accounting software continue to develop. Nevertheless, the trend directionality remains clear.
Stablecoins are not merely an improvement upon cross-border payments for businesses; rather, they are a complete paradigm shift. The 24/7 access, massive cost savings, and final settlement make stablecoins a game-changing tool for international money transfer.
Ready to Lead the Conversation in Modern B2B Payments?
CIO Bulletin empowers your organization to gain the market visibility it deserves while staying at the forefront of digital treasury innovations reshaping global commerce. Share your payment insights with industry leaders, stay ahead of the cross-border curve, and turn your financial expertise into a defining industry milestone!
Subscribe today for exclusive insights: https://ciobulletin.com/subscribe
Enhance Your Brand Presence: Advertise with us at
https://ciobulletin.com/advertise


 consultants ltd.jpg)


Comments