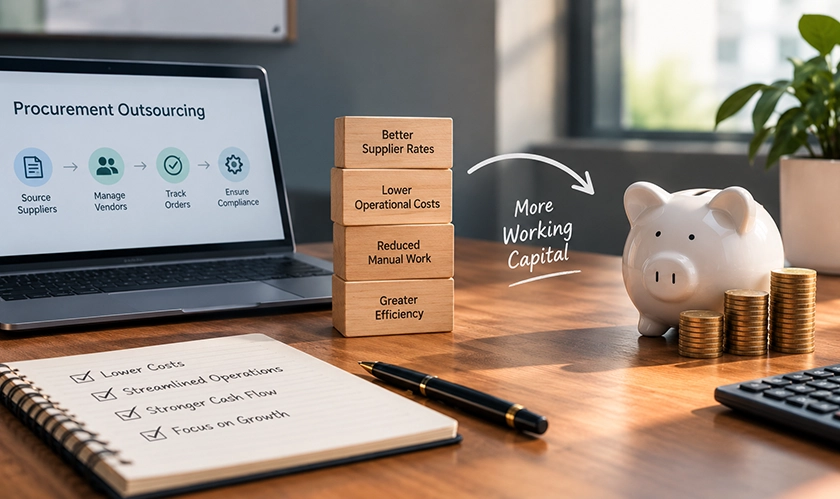
Home Platforms News How Outsourcing Procurement Ca...
CIO Bulletin
,
23 October, 2026
Author:
Guest
A lower unit price can leave a company with less cash and a higher real cost. A cheaper quote that arrives with a 500-unit minimum, a 50 per cent deposit and a 5 per cent reject rate is not a saving; it is a loan to your supplier. That is the question behind procurement outsourcing: can external sourcing and supplier-management support release cash and lower overseas purchasing costs without weakening financial control?
The honest answer is conditional. Value comes from changing inventory commitments, payment timing and purchasing execution, not from outsourcing alone. This article takes a cash-first view, showing which changes release working capital, how to separate that one-off release from recurring savings after provider fees and supply risk, and which handful of measures let you judge a pilot with confidence.
How Outsourcing Procurement Can Free Up Working Capital and Cut Hidden Costs for Growing Finance Teams
Procurement outsourcing here means external support for sourcing and supplier management. It does not mean outsourcing your finance function, and it is not simply a way of buying cheaper goods. Suitable tasks include supplier discovery, qualification, quotation comparison, negotiation support and day-to-day order coordination, all of which demand time and overseas presence that growing SMEs often lack.
One practical route is working with a global sourcing company, which can support supplier discovery, qualification and ongoing coordination when internal teams lack overseas purchasing capacity. The model is a way of executing the work, not a transfer of accountability.
That is why certain controls should stay with you: budgets, final supplier approval, contractual commitments and payment authority, with documented responsibilities and escalation routes. When choosing a provider, treat the following as requirements rather than assumptions: transparent fees, disclosure of supplier commissions and relationships, access to supplier and order information, and regular reporting. Not every provider offers all of these, and those that don't leave you with less visibility than you started with.
Start with the cash conversion cycle: inventory days plus receivables days minus payables days. Purchasing changes mainly act on inventory and payables, and they don't speed up customer collections, so any claim that sourcing support fixes receivables should be discounted.
Smaller minimum orders and phased deliveries can reduce average stock and upfront exposure, but only if commitments and payment schedules change with them, since splitting a shipment achieves nothing for cash if the whole order is still prepaid. Likewise, shorter and more reliable lead times reduce pipeline inventory and the buffer you hold against uncertainty, subject to who owns the goods in transit and what service levels you need.
Payment terms are the second lever. Smaller deposits, milestone payments or negotiated credit terms defer outflows, yet they must be weighed against supplier viability, possible price increases and lost early-payment discounts. Blanket extensions are not a strategy, because a stretched supplier may cut corners or lift prices.
Finally, keep the accounting honest. Releasing cash tied up in stock reduces the working capital you need, but it is a one-off movement rather than recurring income, and a lower unit price alone says nothing about a shorter cash cycle.
Build one comparable cost view that covers purchase price, freight, duties, currency exposure, inspection, defects, rework, emergency shipments and internal purchasing administration. Keep provider fees visible as their own line rather than buried in a quotation, so the comparison stays fair.
This matters because a lower quote can become a higher total cost. Expensive transport, an unfavourable exchange-rate move, rejected goods or repeated corrective work can each erase a unit-price advantage, so compare like with like, using equivalent specifications, the same delivery responsibilities and consistent exchange-rate assumptions.
The most revealing metric is landed cost per accepted unit, because it divides total cost by the goods you can actually sell or use, which exposes the effect of rejects. Show administration and other wider operating costs alongside it so the full economics remain clear.
Finally, make the trade-off explicit. Smaller orders may release inventory cash but raise freight or unit costs, and neither purchasing pattern is inherently better, so assess the cash benefit and the cost penalty together.
Measure hidden costs per accepted unit, not the supplier's quoted price
Uncertainty is what forces businesses to hold excess stock, so tackle it first. The practical controls are to verify supplier identity and capability, agree measurable specifications and acceptance criteria, and use pre-shipment checks to catch problems before dispatch or final payment, where contract terms allow. Better quality and delivery consistency mean fewer replacement orders and emergency shipments, and potentially a lower safety-stock requirement, though inspection and qualification carry their own costs.
For important products, develop qualified alternative suppliers, allowing for tooling, sampling, qualification expense and switching lead times. An untested supplier list is not operational resilience.
Be clear about the limits too. Outsourcing does not remove logistics disruption, supplier failure, currency exposure or demand uncertainty, so reduce stock only once performance evidence supports it, and keep buffers suited to each product's criticality and replenishment risk.
Choose a repeat-purchase category with clear specifications, a measurable cash or cost problem and manageable disruption risk. Set a representative baseline, and run the pilot across complete replenishment cycles rather than judging a single shipment.
Track a compact scorecard: inventory days; deposit requirements and actual supplier payment terms; landed cost per accepted unit; defect rate; and on-time, in-full delivery. Compare like-for-like volumes and specifications, adjusting for seasonality, currency movements and product mix.
Calculate recurring net savings as comparable baseline costs minus ongoing outsourced-model costs, including provider fees, retained internal work and extra inspection or logistics. Show transition, onboarding and supplier-qualification costs separately so first-year value and payback are clear, and report working-capital release on its own line, covering inventory, supplier advances and payables. Never count released stock cash as profit, and count redeployed staff time as a payroll saving only if spending actually falls.
Agree financial targets, service thresholds, reporting ownership and exit arrangements before starting. Scale where net value justifies fees and transition costs, cash benefits are evidenced, and quality, reliability and financial control remain acceptable; otherwise, revise or stop.


 consultants ltd.jpg)


Comments